Is Minimum Liability Coverage Enough?

Lisa Broadbent • April 1, 2022
Two toy cars, one blue and one yellow, facing each other. Two white figures are standing between the cars.


If you’re reading this, chances are you live in a mandatory liability state. What does that mean? It means that to own and operate a registered motor vehicle in your state you are required to maintain a minimum amount of auto liability insurance. I’m guessing this isn’t news to you. You’ve likely been asked for proof of insurance at various times when dealing with law enforcement or your local vehicle registration department. So, let’s assume you’ve satisfied your local government’s minimum liability requirements…

Does this mean you have enough protection?

While I respect the authority and the hard work of elected officials, it’s a scary thing to assume they know how much liability protection you need. While they may have put a minimum requirement in place, it’s up to you to make sure your minimum coverage needs are met. So how do you do that?

In most cases, there’s no exact dollar amount of necessary coverage that can be pinned down. It’s a fluid situation. Your coverage needs are affected by ever-changing factors that may sometimes be beyond your control. Let’s look at some numbers to illustrate the point:

  • As of January 2021, the average transaction price associated with new vehicle purchases is over $40,000 with a surprisingly high number of these transactions being greater than $100,000.
  • On average, 3,287 vehicle-related deaths occur each day in the US. The average financial cost of each of these deaths is $1.7 million.
  • The average cost of non-fatal disabling injuries due to a motor vehicle accident is $98,400.
  • The average court-awarded settlement related to an auto accident claim is $77,600 when the claimant has legal representation.

Based on the statistics above, let’s look at an example…

In Alabama, the required minimum liability coverages are:

  • $25,000 Bodily Injury Liability Coverage per injured person
  • $50,000 Bodily Injury Liability Coverage for all injured persons combined
  • $25,000 Property Damage Liability Coverage

So, let’s say your auto insurance policy provides these required levels of coverage and you’re found to be at-fault in an auto accident. Here are the details:

  • The other party’s 2021 GMC Yukon Denali is damaged beyond repair. Cost – $85,000.
  • There were three occupants in the other vehicle. Two of them sustained disabling injuries. The third occupant was killed. Cost $1,896,800.
  • Your vehicle can be repaired, but the cost will be approximately $10,000.

Since your auto insurance policy provides only the required minimum coverages, you have no coverage for damage to your own vehicle. So that $10,000 repair bill is on you. But that’s the least of your worries. The sum of your liabilities comes to $1,981,800. Of that amount, your insurance policy will pay $75,000. That leaves the remaining balance due of $1,906,800 sitting squarely in your lap.

Your financial future just evaporated.

“But wait… I had the amount of coverage the government said I had to have.” Yes, you did. But it wasn’t enough. And this example didn’t even address things like lost wages, pain and suffering, possible punitive damages…

A simple conversation with your insurance agent could reduce or even eliminate these risks for you. But more to the point, purchasing an insurance policy that provides only the required minimum coverage could leave you extremely vulnerable.

Don’t misunderstand us, I’m glad we have legislation in place that requires at least some level of liability insurance. But we should never make the mistake of assuming it’s enough.

Having adequate liability protection requires a thoughtful, personalized conversation with your insurance agent. And if you don’t have that kind of relationship with your agent, please call Lisa Broadbent Insurance at (302) 731-0044 today and we can fix that.
Businessperson shielding a glowing car icon, symbolizing auto insurance protection.
By Lisa Broadbent Insurance • October 20, 2026
Shopping for auto insurance quotes in Middletown, DE? Lisa Broadbent Insurance, Inc. compares carriers to find your best fit. Call (302) 731-0044 today.
Person signing auto insurance documents beside model car and protection shield.
By Lisa Broadbent Insurance • October 20, 2026
Learn Delaware's 2026 auto insurance policy rules for Middletown drivers. Lisa Broadbent Insurance, Inc. offers custom coverage. Call (302) 731-0044 today.
Agent and client discussing an auto insurance policy claim with toy cars in a collision
By Lisa Broadbent Insurance, Inc. • September 25, 2026
Understand your auto insurance policy in Middletown, DE. Lisa Broadbent Insurance covers DE minimums, PIP, and lapse penalties. Get a local quote today.
Depiction of a situation related to a car collision or insurance claim
June 30, 2026
Automobile insurance in Hockessin, DE, can shield you from repair bills, medical costs, and liability claims. Call Lisa Broadbent Insurance, Inc. to find the right coverage today.
Hands using a pen and calculator over a clipboard with a blue toy car, suggesting auto insurance paperwork
April 27, 2026
Avoid costly mistakes in automobile insurance with Broadbent Insurance, Inc. Serving Hockessin, DE, drivers. Click here for the best advice and coverage tips!
Finger pressing a car insurance start button on a dashboard.
April 13, 2026
Need commercial vehicle insurance in Hockessin, DE? Lisa Broadbent Insurance, Inc. can help protect your business. Call us at 302-731-0044 today.
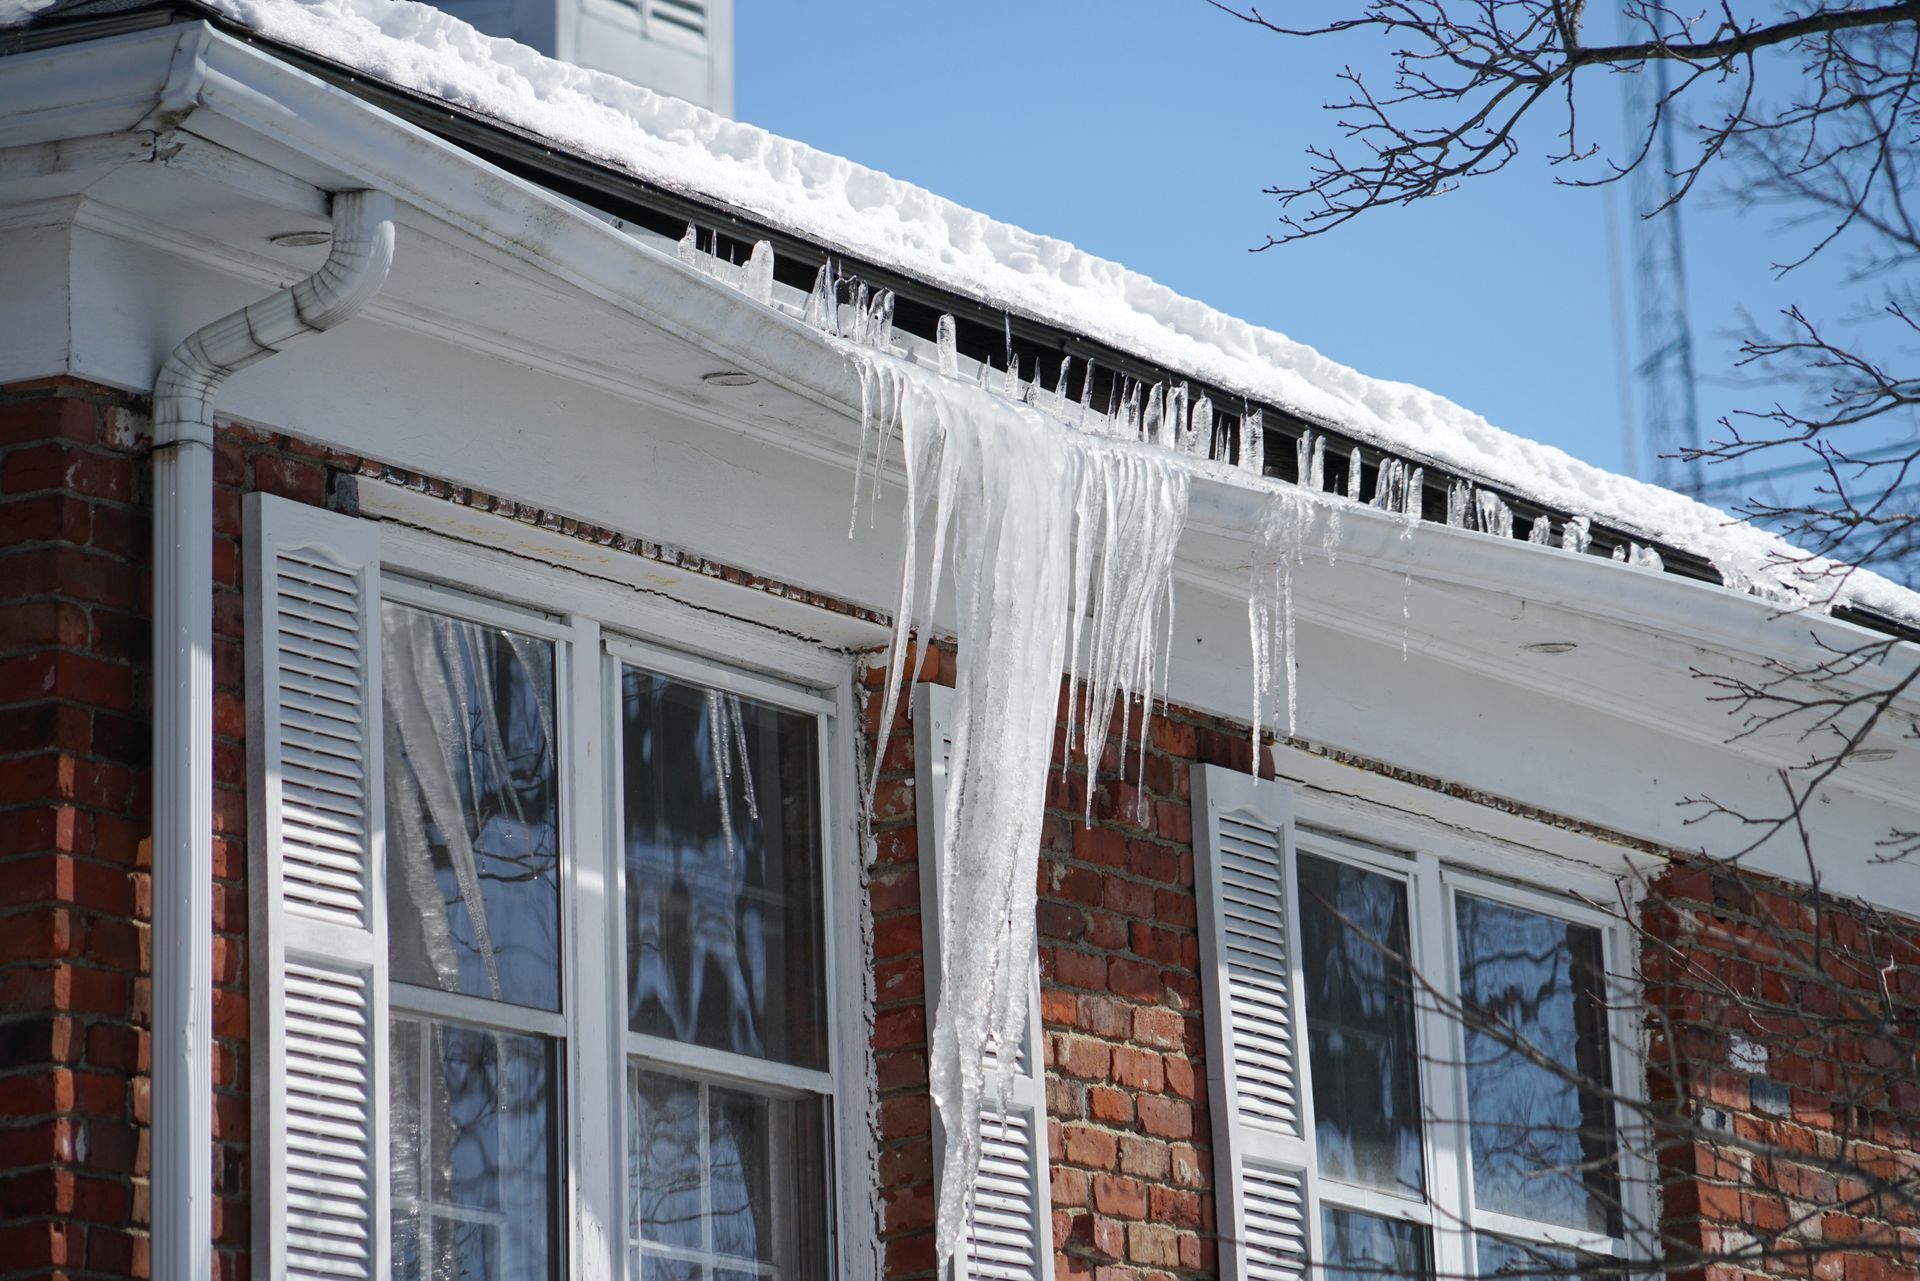
Icicles hanging from a snow-covered roof of a brick building with white shutters.
By Lisa Broadbent • January 5, 2026
Taking precautions to prevent ice dams is an important part of preparing your home for winter weather. Knowing what an ice dam is , minimizing the conditions that allow one to form and removing an ice dam as soon as you spot one can help prevent serious damage to both the roof and the inside of your home. Take action before snow starts falling An ice dam may develop during the cold winter months if warm air from your home or attic melts snow on your roof. In freezing temperatures, the melted snow may refreeze once it reaches the colder edge of the roof. Keeping the temperature of your attic at 32°F or below can help prevent snow from melting and ice dams from developing. The following are some steps you can take to help prevent the snow melting-and-freezing cycle that often causes ice dams: Insulate your attic. Be sure your attic is properly insulated to help prevent warmth from escaping through ceilings. Whenever possible, an insulation value of R-40 is recommended. Prevent air leaks. Check and seal any openings where warm air or heat could escape into the attic, such as insulating or caulking around vent pipes, exhaust fans, chimneys, attic hatches and/or light fixtures. Improve ventilation. Increase the number or size of attic, roof or soffit vents that allow cold air to circulate and flush warmer air out during the winter. Install a water-repellent membrane. When replacing the roof covering, install a water-repellent membrane underneath the shingles. This acts as an extra barrier that helps prevent water from seeping inside the building should an ice dam form. Tips to help prevent ice dams through the winter Ice dams can sometimes form despite your best efforts to keep your roof at the proper temperature. Be sure to monitor the weather and maintain your roof throughout the colder winter months for additional protection against ice dams, such as: Clear gutters and downspouts. Prevent water from accumulating and possibly freezing in your gutters by cleaning leaves, debris and snow accumulation from in and around gutters and downspouts. Making sure that your gutters are properly pitched can also help prevent the collection of water in low spots and help reduce the potential for ice buildup in gutters. Remove snow accumulation from your roof after every storm. Whenever possible, use a roof rake to clear snow about three to four feet from the edge of your roof soon after each storm. Snow accumulation along the edge of your roof increases the likelihood of an ice dam developing, which prevents water from draining off the roof. This water can then back up underneath roof shingles and make its way into your home. Remove ice dams as soon as you spot them. Check your roof often and know how to help identify and remove an ice dam. CAUTION: Avoid using a ladder in snowy and icy conditions. This can be extremely dangerous and is best left to the professionals. For questions or concerns about insurance to protect your home’s roof, please contact us at 302-731-0044 , or email lisa@broadbentins.com . Our agents and staff are available Monday-Friday, 8 a.m. to 5 p.m. ET, with the exception of holidays.
Hands forming a protective gesture over a wooden car model placed on an insurance document.
November 27, 2025
Lisa Broadbent Insurance, Inc., in Hockessin explains why your auto insurance policy needs a yearly review. Call 302-731-0044 or click here to learn more.
A businessman covering a toy car with his hands, symbolizing auto insurance protection and care.
November 4, 2025
Discover trusted auto insurance in Hockessin from Lisa Broadbent Insurance Inc. Contact 302-731-0044 for expert and professional local coverage today!
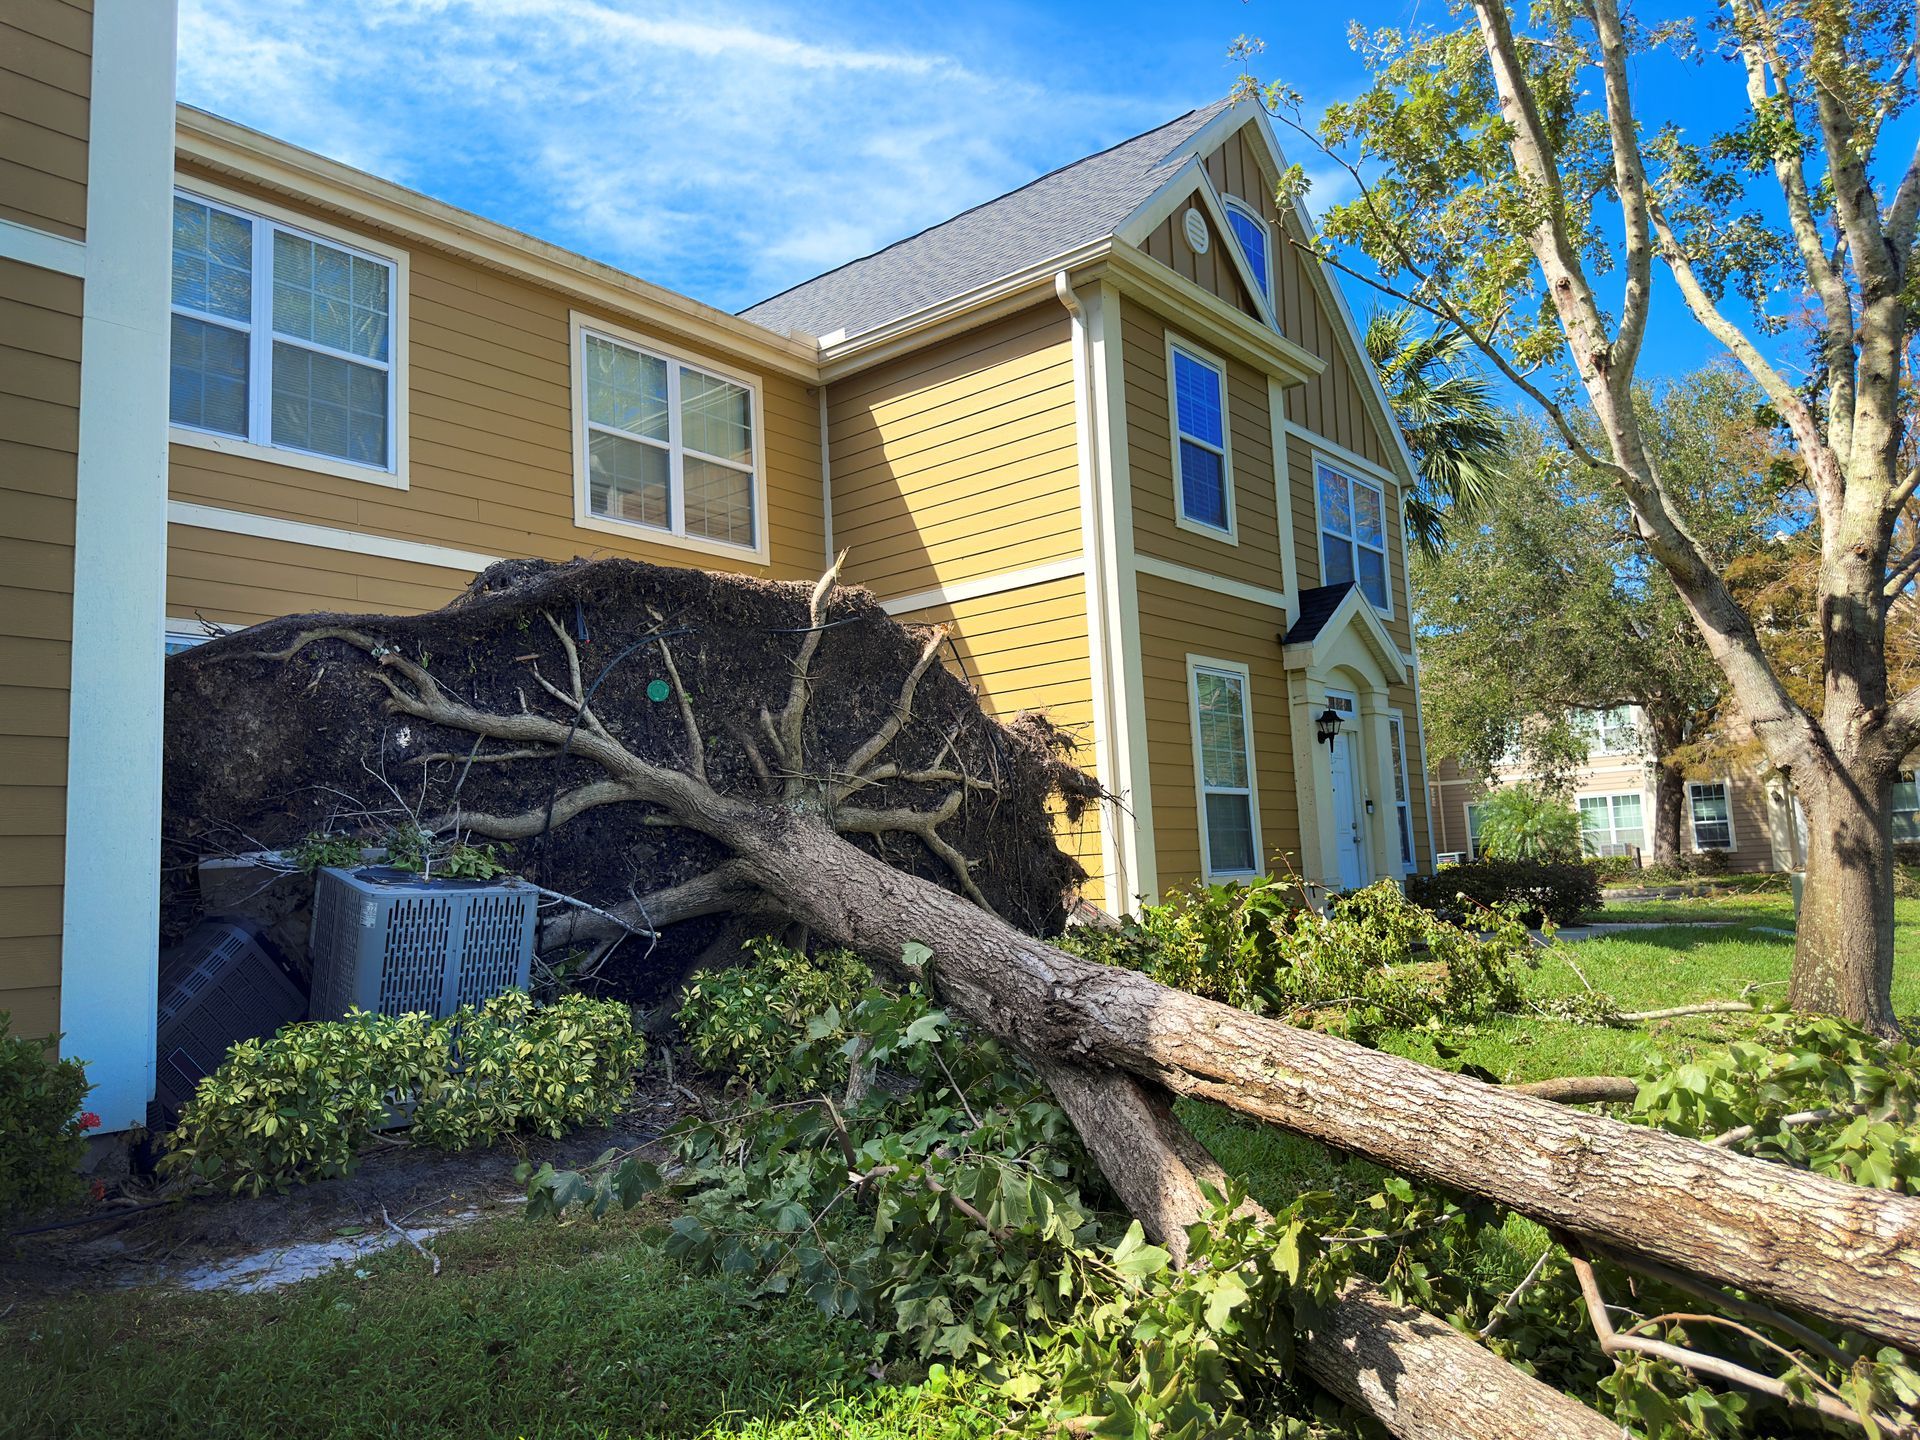
A tree fell onto a two-story yellow house after a storm.
By Lisa Broadbent • July 18, 2025
Check your hurricane insurance coverage today.
Show More